Mobile Money Fintech Ltd CEO calls for greater financial inclusion and stronger fraud protection in Ghana’s fintech sector
Date: 2026-10-12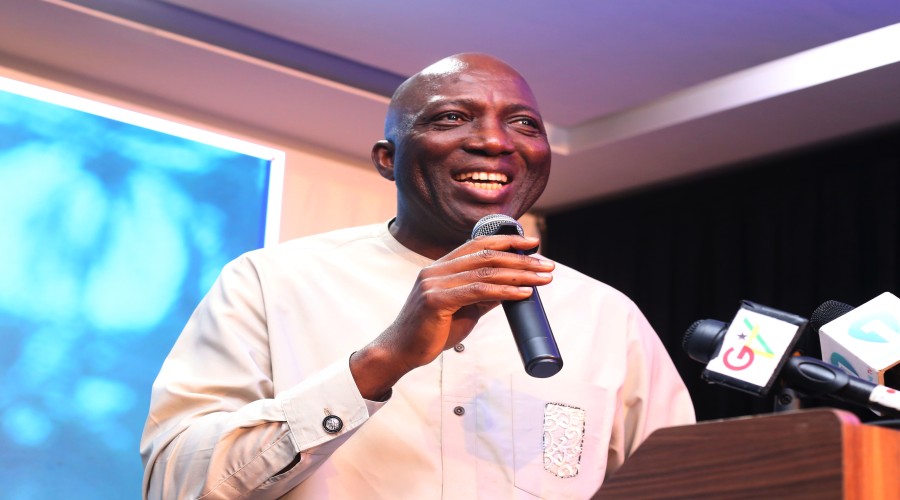
By: Nana Appiah Acquaye
The Chief Executive Officer of Mobile Money Fintech Limited, Haruna Shaibu, has called for greater financial inclusion, stronger fraud protection and deeper collaboration across Ghana's financial Technology ecosystem, highlighting the need to extend digital financial services to underserved communities and micro-enterprises.
Speaking at the Fintech
Media Development Series in Accra, held under the theme “Understanding Fintech,
Building Trust, Telling the Real Story”, Shaibu said the industry must focus
not only on business growth but also on improving financial health, protecting
customers and expanding opportunities for small businesses.
“Our mission remains very,
very simple, but very entrenched in the Ghanaian financial ecosystem,” he said,
noting that mobile money had evolved from a peripheral player into an important
part of Ghana’s financial system.

Shaibu said
micro-enterprises remained significantly excluded despite progress in expanding
digital financial services. He called for greater efforts to bring small
traders and entrepreneurs into the formal financial ecosystem, enabling them to
grow their businesses, create employment and contribute to Ghana’s economic
development.
He also highlighted
opportunities to deepen mobile money usage, noting that global adoption figures
showed a significant gap between registered accounts and active users. Citing
GSMA reports, he said approximately 2.3 billion mobile money accounts existed
globally, but only about 600 million were active, indicating room to increase
the frequency and range of digital transactions.
Shaibu identified digital
lending as an area of growing opportunity, particularly for individuals and
micro-businesses that struggle to access financing. Digital transaction
records, he said, can help providers assess customer behaviour and develop
credit-scoring models that support access to loans. He added that the vast
majority of the company’s customers repay their loans, while stressing the
importance of addressing abuse of the system responsibly.
He also called for
innovation in digital insurance, arguing that simply making traditional
insurance products available through mobile money platforms was not enough to
drive adoption. Instead, he said, providers should explore embedding insurance
into customers’ everyday transactions to make coverage more accessible.
Fraud and cybersecurity were
among the major challenges he highlighted. Shaibu recounted an attempted online
scam involving a fake pizza order that sought to obtain his personal
information and take over his WhatsApp account. Although device binding on his
mobile money account provided an additional safeguard, he said the incident
demonstrated how fraudsters exploit vulnerabilities across different digital
platforms.

“The responsibility on all
of us is to keep educating our customers and also build the necessary tools
that will help us address some of these things in our ecosystem,” he said.
Shaibu said addressing fraud
required coordinated action across financial services, telecommunications and
other digital platforms, as attacks increasingly move between systems. He
identified artificial intelligence as a potential tool for detecting and managing
fraud in real time, provided organisations can collaborate and share relevant
information.
Looking ahead, he identified
several developments likely to shape the fintech industry, including artificial
intelligence for fraud prevention, open finance, embedded financial services,
digital assets and cross-border interoperability.
He said embedded finance
could help customers access savings, investment and insurance products through
routine transactions, reducing the barriers associated with purchasing such
services separately. He also highlighted the potential of tokenised assets to
allow people to invest in smaller fractions of assets such as gold, making
investment opportunities more accessible.
On cross-border payments,
Shaibu said reducing regulatory and operational friction could unlock
opportunities for African businesses, particularly micro-enterprises seeking to
benefit from regional trade and the African Continental Free Trade Area.
He cited Ghana’s mobile
money ecosystem as an important example of digital financial infrastructure,
reporting that the industry processed GH¢3.37 trillion in transactions as of
August 2026. However, he cautioned that the figure represented total transactions
across the ecosystem, including agent-to-agent transfers, merchant payments and
consumer transactions, rather than money held in customer accounts.

He also said Mobile Money Fintech Limited processed more than 26 million transactions daily, making operational resilience, platform reliability and consumer protection essential. The company invested in a major platform upgrade in the previous year to expand capacity and support continued growth in Ghana’s fintech sector.
Shaibu said the company was
committed to working with other fintech firms, dedicated electronic money
issuers, industry associations and regulators to strengthen the ecosystem. He
pointed to stakeholder engagements, the Bank of Ghana-led 3i Summit and the
company’s group fintech summit as platforms for collaboration, innovation and
expanding opportunities for Ghanaian businesses across African markets.
“Trust is the centerpiece of
what we do,” he said, describing fraud prevention and cybersecurity as areas in
which investment could not be compromised.
He called for collective
efforts to build a secure, inclusive and sustainable financial ecosystem that
supports customers, strengthens businesses and creates lasting economic
opportunities for Ghanaians.